Sample Listing
Most listings only market the house.
This one is built to market the opportunity behind the house.
The goal is not just to lower the price. The goal is to create more visibility, show a more affordable monthly payment, and help more buyers see the home as a real option.
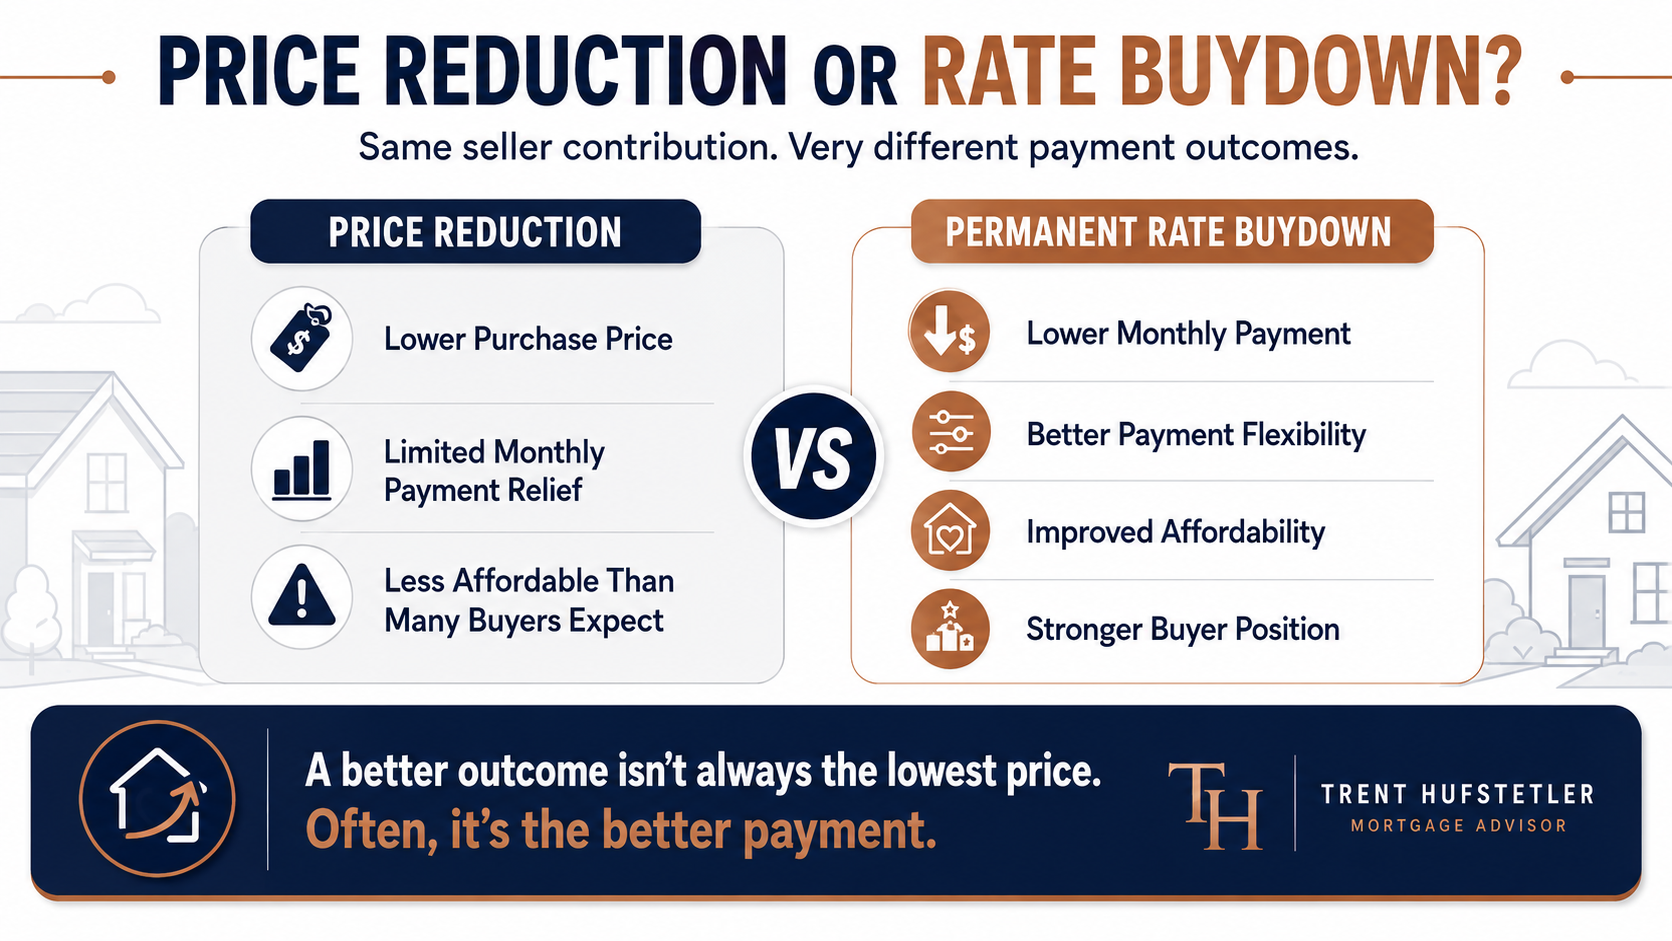
A lot of sellers assume the only way to improve affordability is with a price reduction. But in today’s market, buyers are usually looking at one thing first: the monthly payment.
This example shows how the same seller contribution can be used in different ways. One option may lower the price. Another may create a stronger payment impact for the buyer.
The point is simple: before assuming the next move is another price drop, it helps to understand how affordability can be marketed as part of the listing strategy.
The price, your down payment, and your payment at today's rate.
Loan details
A buydown lowers your rate for the life of the loan.
Savings details
The seller can cover the cost with a Buydown Cost (Seller Credit).
Your buydown frees up money every month for the things that matter to you.
Summary details
| Today | With the Buydown | |
|---|---|---|
| Interest rate | ||
| Monthly payment | ||
| Buydown cost | ||
| Seller pays | ||
| You pay |
This walkthrough is for example purposes only and is not an offer to lend. Example payments shown here include principal and interest on a 30-year fixed loan, and don't include taxes, insurance, or mortgage insurance. Actual rates, payments, and costs vary by lender and buyer.
Frequently Asked Questions
1. Can a rate buydown help sell a property faster?
It can help create more interest when affordability is one of the reasons buyers are hesitating. A buydown does not guarantee a faster sale, but if the monthly payment becomes more attractive, more buyers may be willing to schedule a showing, revisit the property, or write an offer.
2. Why would an agent talk about a buydown instead of just recommending a price reduction?
A price reduction is one option, but it is not the only option. Sometimes the seller is already considering giving up money. The question is whether those dollars are better used to lower the price or improve the buyer’s monthly payment. Running both scenarios helps the agent give better advice.
3. How can this help with listing visibility?
If the listing can be marketed with a more attractive payment strategy, it may give buyers and buyer’s agents a reason to take a second look. Instead of only saying “price improved,” the listing can also tell a better affordability story.
4. Does a rate buydown expand the buyer pool?
It can, depending on the buyer’s situation and the loan program. If the lower payment helps more buyers feel comfortable or potentially qualify, the listing may become realistic for people who previously felt priced out.
5. Is a seller concession always better than a price reduction?
No. Sometimes a price reduction is still the right move. The point is to compare the numbers before defaulting to one strategy. A seller concession, price reduction, or rate buydown can each create a different result.
6. When should an agent consider running a buydown strategy?
It makes sense to look at it when showings have slowed down, buyers are giving payment-related feedback, the listing is sitting longer than expected, or the seller is already considering a price adjustment. Before dropping the price again, it is worth seeing what the same dollars could do for affordability.
Want to see what this could look like on one of your listings?
Every property is different. Every seller has different goals. And the right affordability strategy can change depending on the numbers.
We can put together a customized affordability review that shows:
Price reduction scenarios
Seller concession options
Monthly payment comparisons
Estimated buyer impact
Ways to improve affordability
The goal is not to replace your pricing strategy.
The goal is to help you see the full picture before automatically moving toward another price reduction.
Jane Smith
XYZ Real Estate
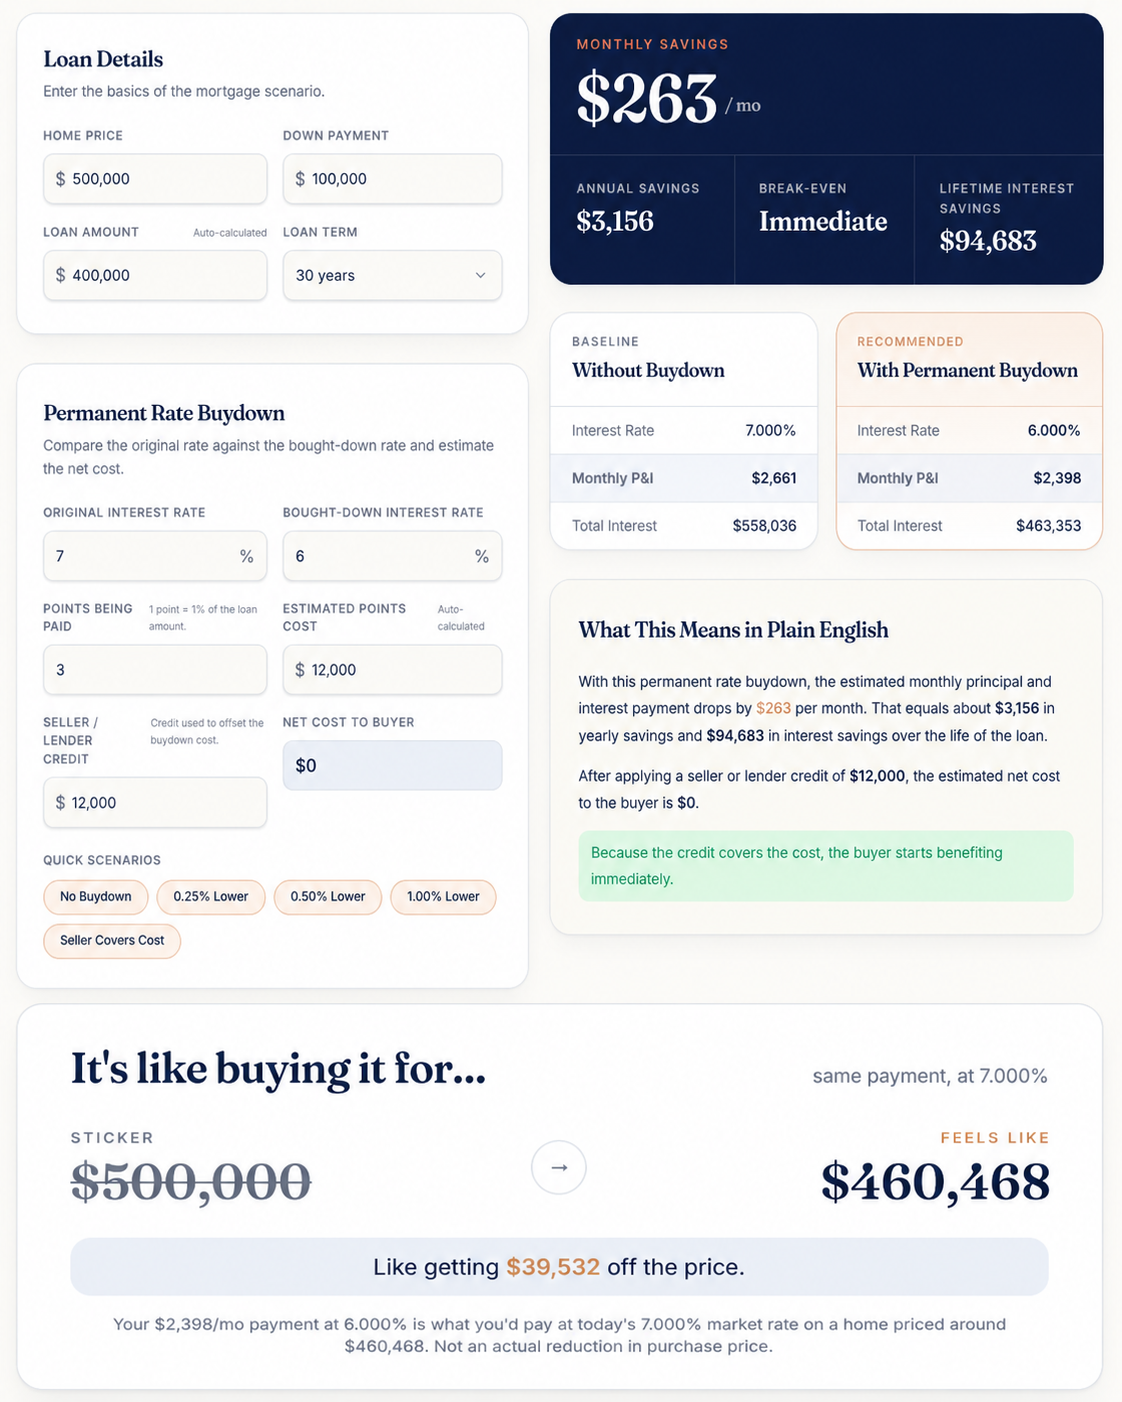
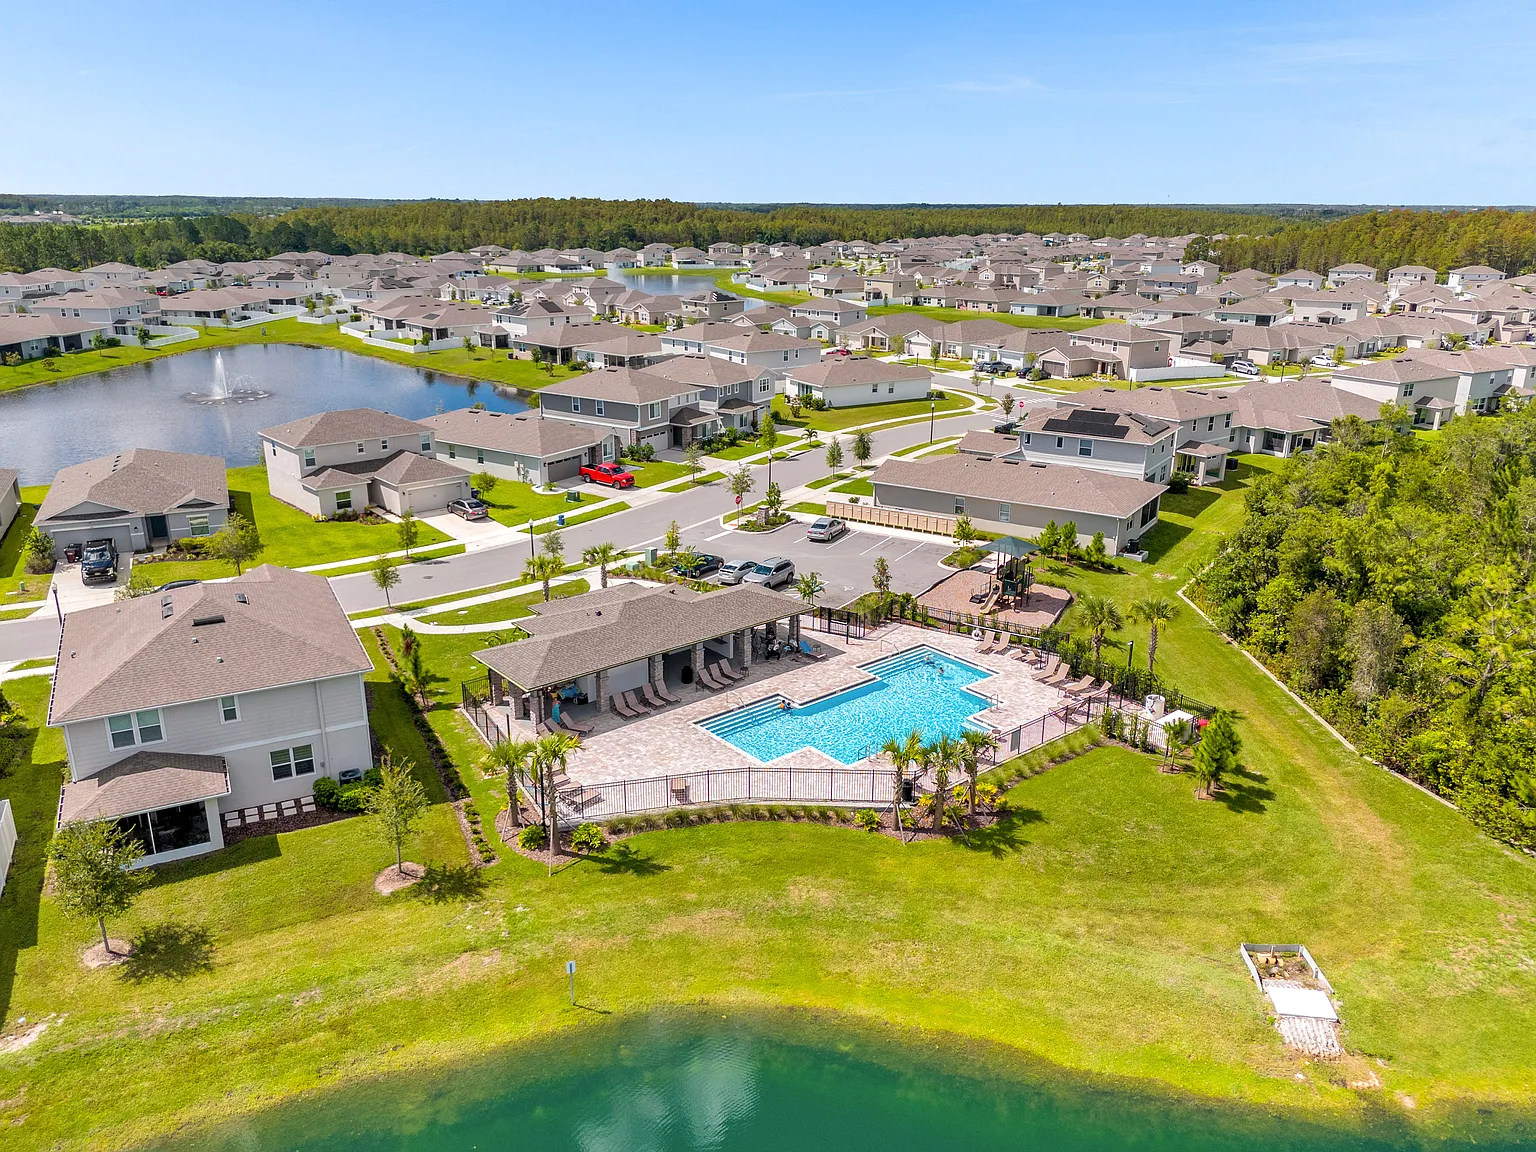
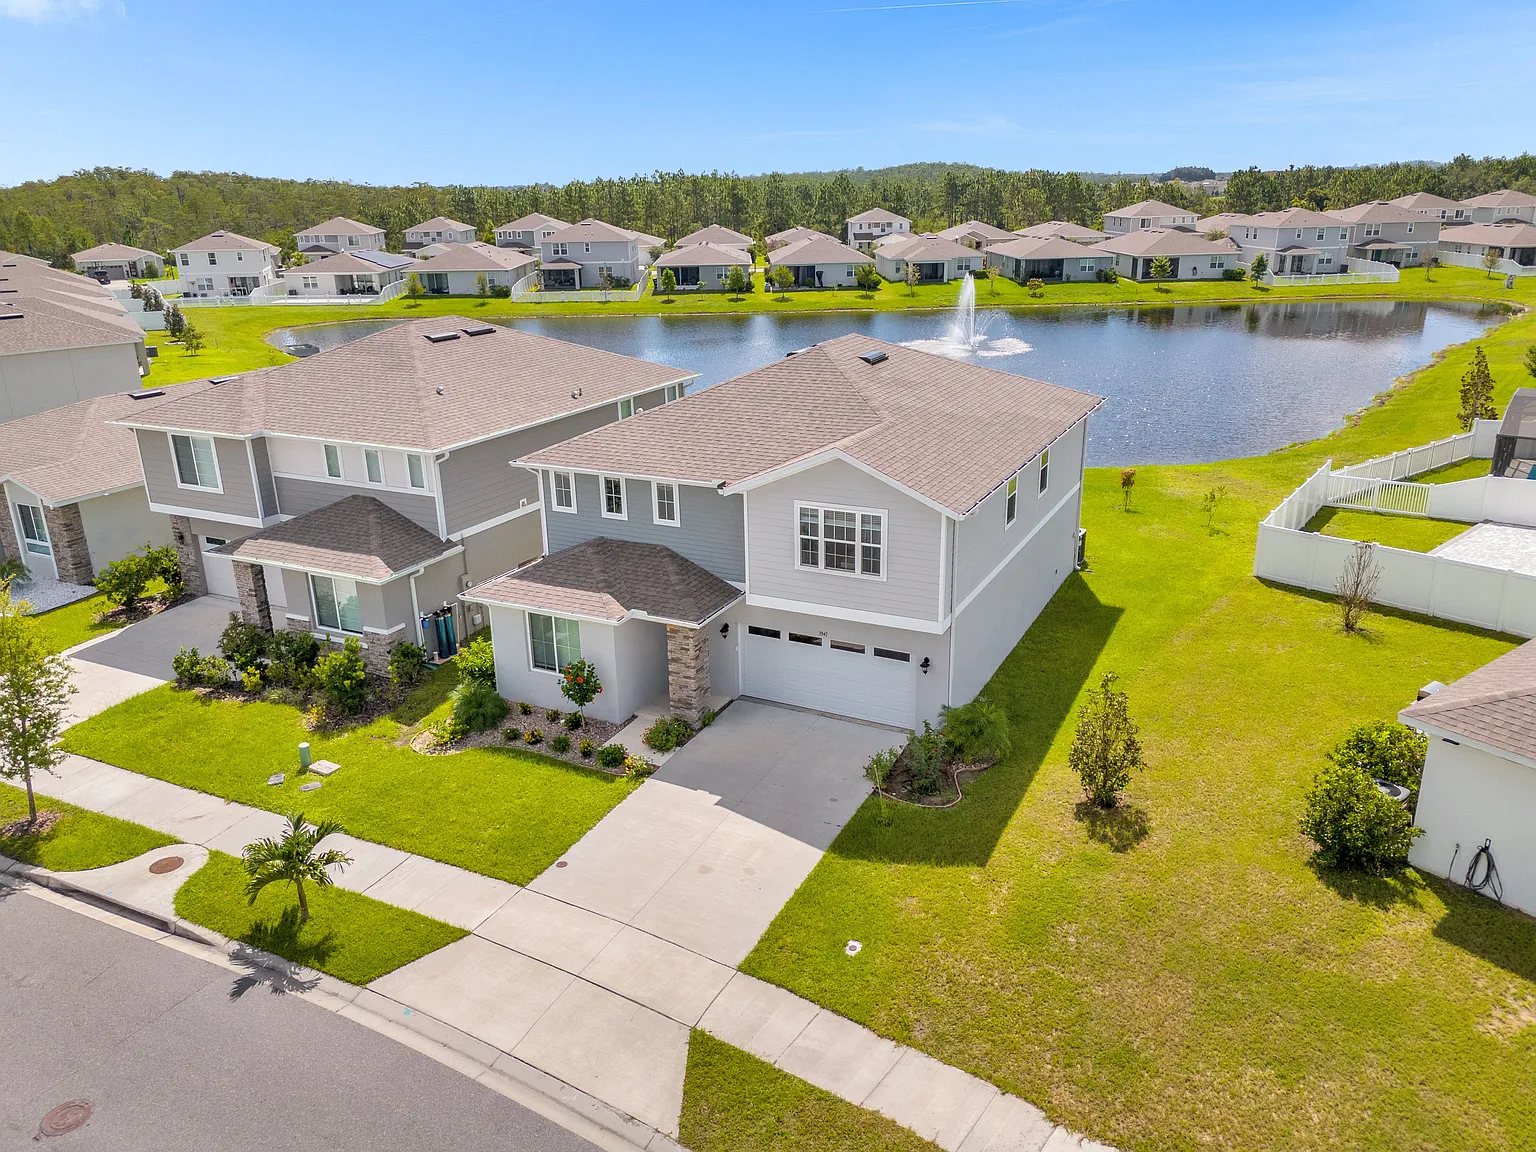
Photo Gallery
Share
Sample Listing