Doctor loans
Bring Me Your Medical Professional Buyer Who Put Their Search on Hold
Student loans, a future job start date, or a move into contract work may be worth a closer look. Specialized mortgage options can extend beyond physicians to certain nurses and other medical professionals.
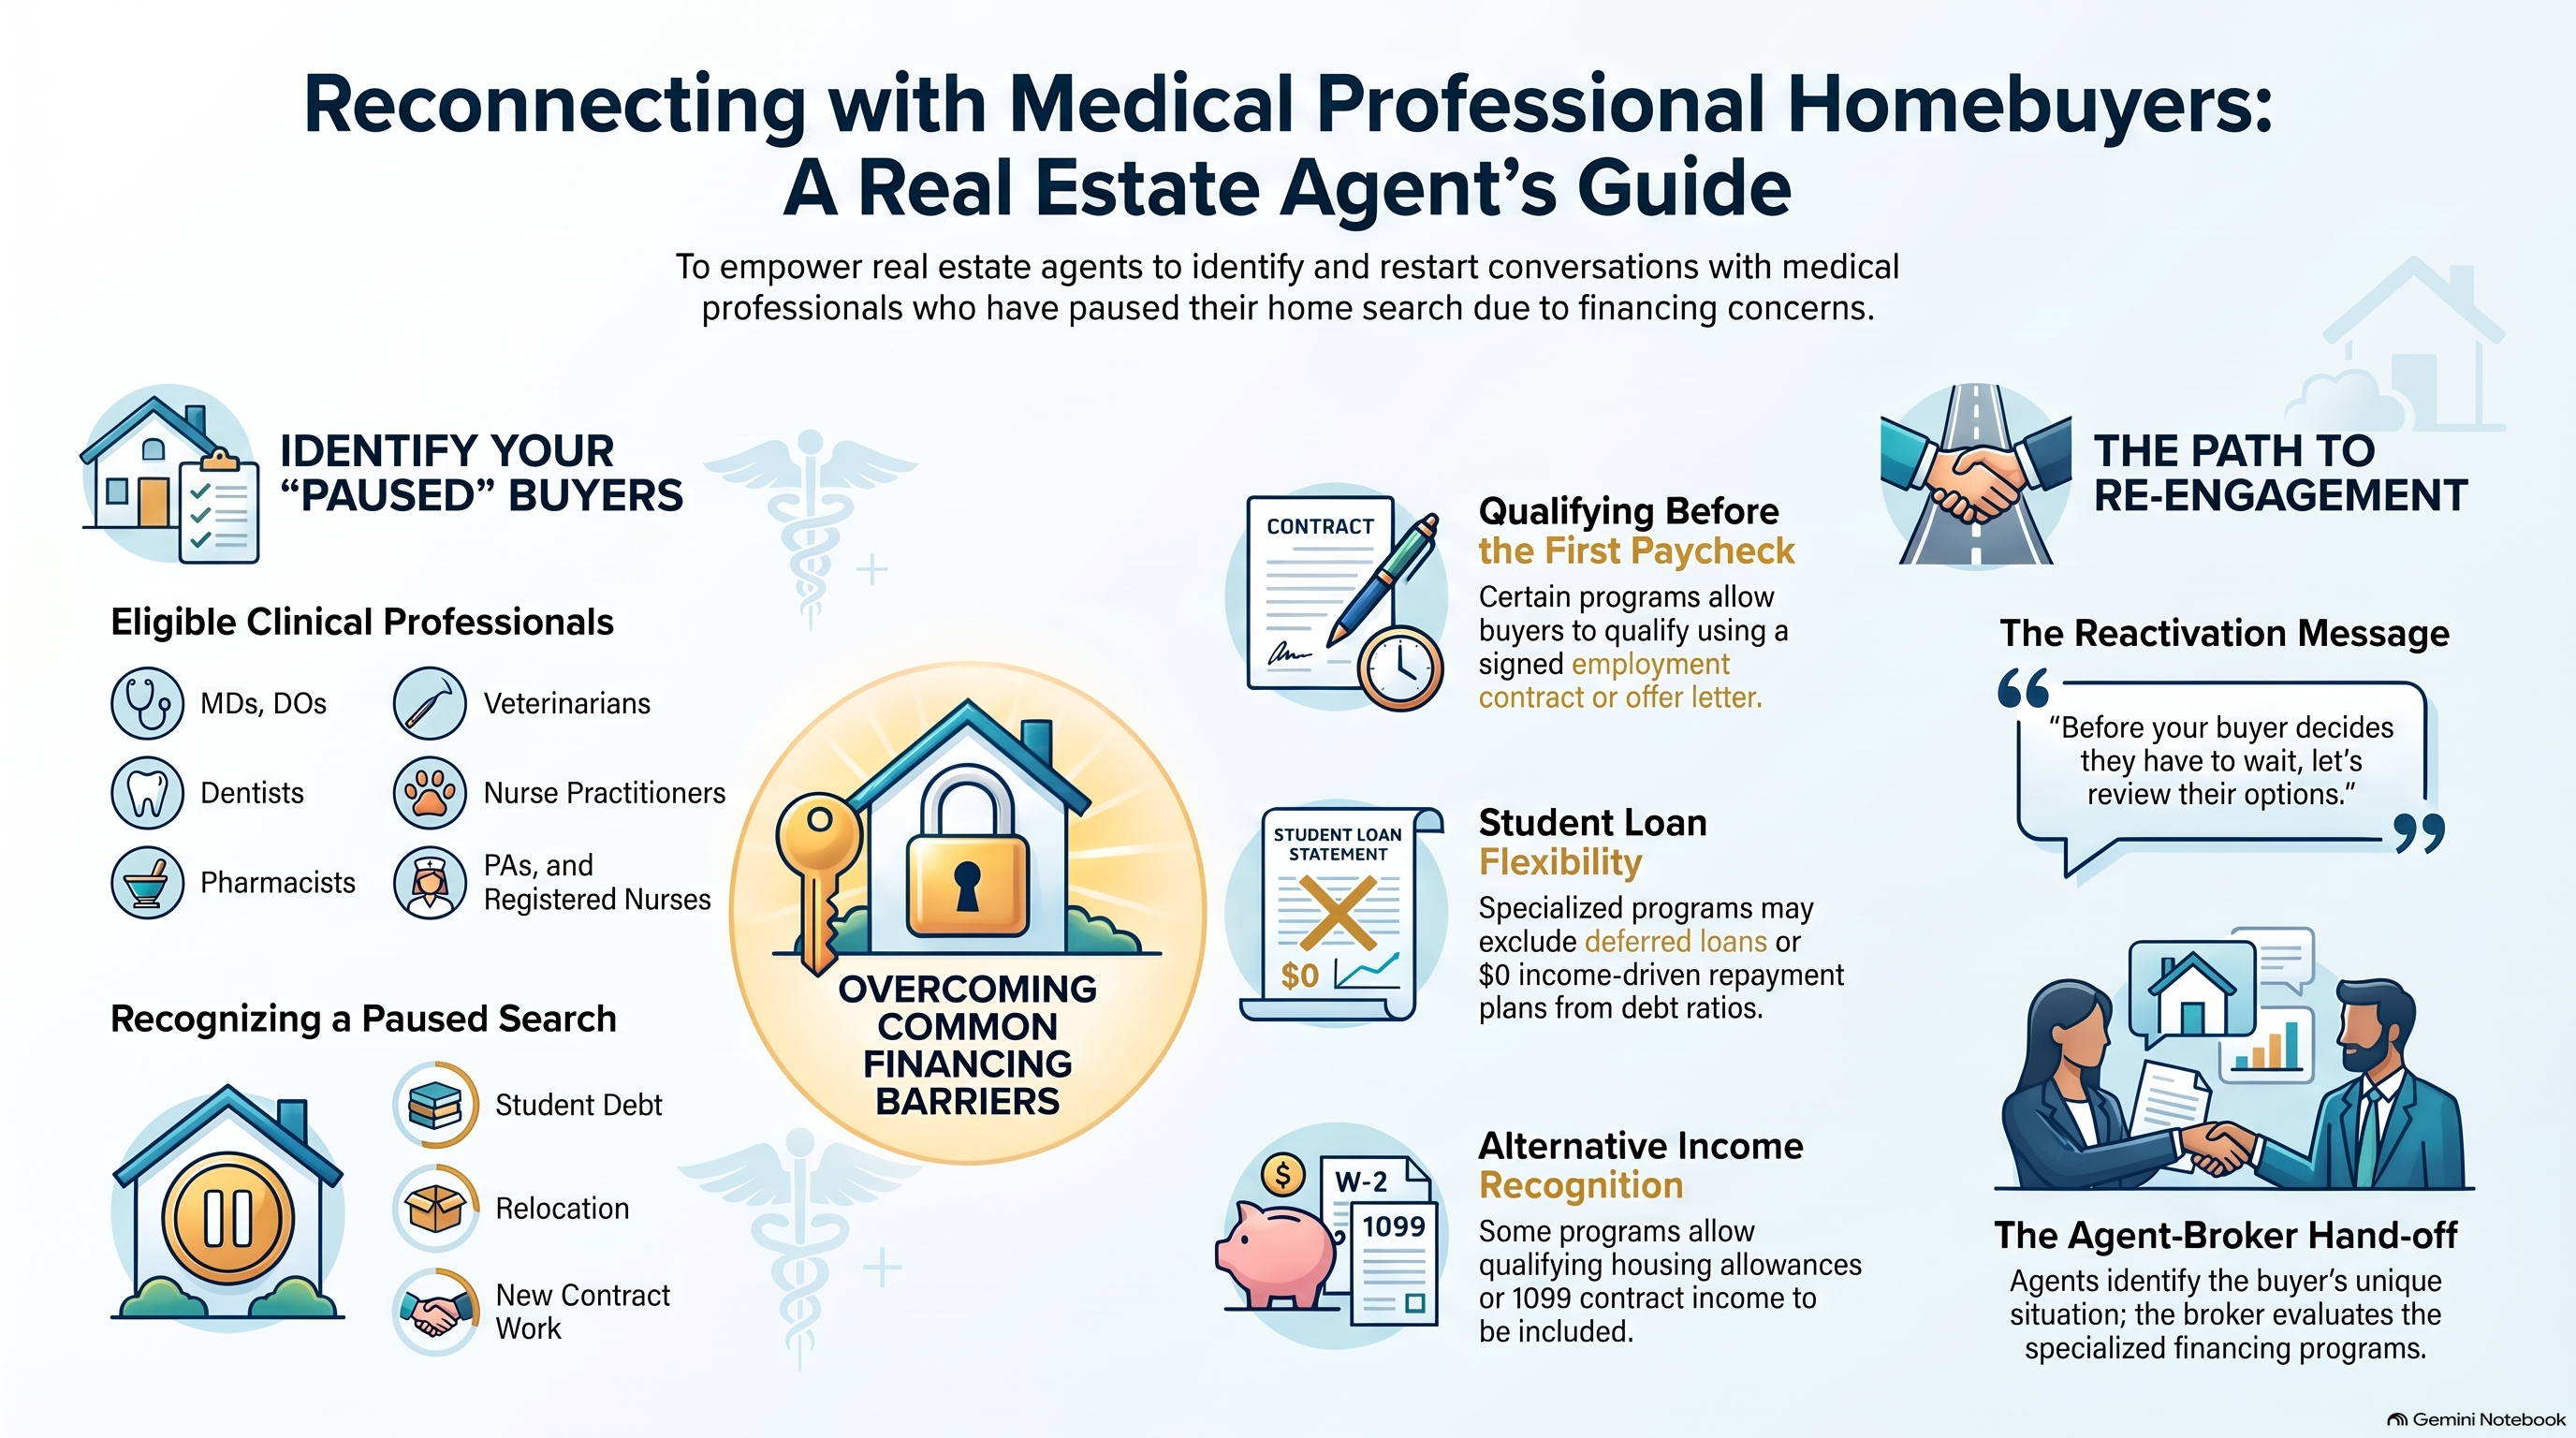
Before your buyer decides they have to wait, let’s review their options.
As your mortgage advisor, I’ll review the buyer’s circumstances and explore the programs that may fit. Start with their profession, buying location, employment timeline, and the concern that put their search on hold.
Article: A New Conversation for Buyers Who Put Their Search on Hold
A medical career can involve years of training, student debt, relocation, and changes in how income is earned. When a buyer pauses their search because of one of these circumstances, an individual mortgage review may uncover options they have not considered.
Recognize the opportunity
Listen for statements such as “My new job hasn’t started,” “My student loans mean I can’t buy,” or “I just switched to contract work.” Certain specialized programs offer ways to evaluate employment contracts, eligible residency or fellowship income, and documented medical contract earnings.
Options may extend beyond physicians and dentists to eligible pharmacists, veterinarians, nurses, advanced practice professionals, and other clinicians. Exact credentials and program requirements matter.
Reconnect with a buyer
Try this message: “I remembered that you put your home search on hold because of your employment timing or financing concerns. There are specialized options for certain medical professionals that may be worth reviewing. Would you like an introduction to my mortgage advisor to see what may be available now?”
Make a useful introduction
With the buyer’s permission, share their profession, purchase location, approximate price range, employment situation, desired timing, and the concern that caused them to pause. The buyer can send financial records directly through the advisor’s secure process.
Build the search around verified options
As your mortgage advisor, I’ll review the scenario and explore programs that may fit. Before an offer, we’ll need to confirm the financing, expected cash needed, property eligibility, and employment timing. A review helps establish the next step; it does not guarantee approval.
Bring me your medical professional buyer who put their search on hold. Before they decide they have to wait, let’s review their options.
Frequently Asked Questions
Are these options only for doctors?
No. Depending on the program and exact credentials, eligible borrowers may include dentists, pharmacists, veterinarians, nurses, nurse practitioners, physician assistants, CRNAs, and other listed professionals. I’ll verify the buyer’s designation and match it with available options.
Can a buyer qualify before starting a new job?
Some eligible borrowers may qualify using a signed employment contract or offer letter. Start-date limits, compensation, contract conditions, employment verification, and reserves apply. Send the scenario for review before setting a closing date.
Do student loans prevent a buyer from qualifying?
Not automatically. Certain residents and fellows using qualifying training income may receive special treatment of student loans in deferment, forbearance, or an eligible documented $0 repayment arrangement. This exception does not apply to every medical professional; other borrowers may need a payment included.
What if the buyer recently became a medical contractor?
Some programs allow eligible borrowers with limited contract-income history to qualify using documented minimum guaranteed compensation. Contract terms, expected work, expenses, tax history, and employment timing must be reviewed.
Can a residency housing allowance count as income?
In some programs, an eligible allowance paid directly to the borrower may count when documentation and continuation requirements are met. A rent credit or payment made to a third party may not qualify.
Is 100% financing available to every medical professional?
No universal financing promise applies. Ask me to verify the available down-payment options, loan limits, credit requirements, and mortgage-insurance terms for the specific buyer. Even if a no-down-payment option is available, closing costs, prepaid expenses, and reserves may still be required.
Can these programs be used for any property?
No. Occupancy and property restrictions vary. Have me review the intended property, especially a condo, second home, or unusual property, before relying on a program.
What should an agent send to start a review?
With the buyer’s permission, share their profession, buying location, price range, employment type and start date, desired timing, and main concern. Financial documents should come directly from the buyer through a secure process.
Does a review guarantee approval?
No. A review helps identify potential options and next steps. Final approval depends on verification, the property, and complete underwriting. Program features vary and may not be combined.